US vet practices are seeing fewer patients and charging each one more, and the companies that supply them are starting to say the price side has gone far enough. That’s the clearest signal from roughly 950 SEC filings and investor documents from 51 public companies (IDEXX, Zoetis, Elanco, Trupanion, Chewy, Tractor Supply and others) between January 2024 and October 2026.
None of these companies own your practice. But they sell the tests, drugs and insurance that pass through it, so their numbers give an early read on where your revenue, your clients and your practice’s value are heading. Here’s what matters most if you own or run a practice.
Fewer visits, bigger tickets
US same-store clinical visits have fallen for three straight years, yet practice revenue keeps edging up. The gap is revenue per visit, which has risen roughly 4–5% a year.
| US practice metric | 2024 | 2025 | 2026 so far |
|---|---|---|---|
| Same-store clinical visits | (2)% | (1.9)% | (1.0)% Q1, (1.3)% Q2 |
| Practice revenue per practice | +3% | +2% | na |
| Diagnostics revenue per practice | +4% | +6% | na |
Source: IDEXX 10-Ks and quarterly prepared remarks.
The visits being lost are mostly wellness visits. IDEXX calls them “the primary constraint,” while sick-pet visits are slightly positive. It blames two things: capacity strain left over from the pandemic surge, and financial pressure on pet owners. Canine checkups alone were down more than 2% in Q2 2026.
What it means for you: if your visit count is flat, you’re beating the market. Growth is coming from what happens inside each visit, especially diagnostics, which grew three times faster than practice revenue in 2025.
Pricing is hitting a ceiling
The market leader in animal health now says veterinary services prices are part of the problem. On its Q2 2026 call, Zoetis’s CEO said visit declines have “occurred alongside price increases that have outpaced broader consumer inflation,” making owners “more selective.” Zoetis then cut its 2026 outlook to an organic sales decline of 1 to 3% and began cutting its own prices.
The longer view backs that up. Trupanion says vet inflation ran +5 to 7% a year for 40 years, then hit double digits three years running from 2022, compounding to more than +40% during that time. Over the past decade, veterinary services CPI rose 65% against 36% for overall CPI (Trupanion 2025 Investor Day).
The good news: most clients still say yes. In an IDEXX survey of about 2,300 US pet owners (June 2025), 93% of financially “very secure” owners accepted a recommended blood test. Even among “financially insecure” owners, 81% did.
What it means for you: another year of double-digit fee increases is riskier than it was. Clients are still accepting care they see as medically necessary; it’s the routine wellness visit they’re skipping or taking elsewhere.
Your next growth wave: the pandemic pets are getting older
The pet boom is over, but its pets are still here. IDEXX estimates the US pet population grew 6%, 4%, 2%, 1% and 0% from 2020 through 2024, adding about 23 million pets. It expects roughly 1% a year from here.
That pandemic cohort is now moving into its highest-spend years. IDEXX calls it a “green shoot”: visits for pets five and older are already growing (Q1 2026), and bloodwork inclusion rises with age.
What it means for you: senior wellness, chronic disease management and age-based diagnostic protocols are where per-visit spend is growing. A practice set up to catch that wave, with senior screening panels, chronic care plans and reminders, is positioned for the next five years.
Retail is angled to steal share in wellness visits and pharmacy
The two revenue lines most exposed to retail are exactly the ones already under pressure: routine wellness and preventive products.
| Retailer | Strategic move | Scale |
|---|---|---|
| Tractor Supply | Bought VIP Petcare (May 2026) | ~2,700 retail clinic sites in 39 states; 1M+ pets a year |
| Chewy | Opened Chewy Vet Care (2024) | 8 clinics in 2024, 18 by end of 2025 |
| Chewy | Online pet pharmacy and health products | $1.45B (2023) to $1.98B (2025) |
| Petco | Vetco and in-store hospitals | About 1,600 Vetco clinics a week; about 300 hospitals |
Sources: Tractor Supply press release (May 2026); Chewy and Petco 10-Ks.
Zoetis also says retail used to offset weaker clinic sales of flea, tick and heartworm products, and no longer does (Q2 2026 call). Tractor Supply now ties vet care, pharmacy (Allivet) and retail together in one loyalty program, a model aimed squarely at rural and price-sensitive clients.
What it means for you: expect competition for the routine wellness visit and the refill, not for surgery or complex medicine. Keeping preventives in-house increasingly depends on convenience (auto-ship, online pharmacy partners) and on wellness plans that bundle the visit with the product.
You have more leverage with suppliers than you think
The drug makers are fighting for share, and clinics are the prize. Elanco raised its 2026 outlook to +6–7% organic growth, with US Pet Health up 11% in Q2 2026 on new products like Zenrelia and Credelio Quattro. Over the same half-year, Zoetis’s US revenue fell 7%.
Zoetis’s CEO described competitors using “higher levels of discounting, rebates, cross-portfolio, bundling” to win patients, and said Zoetis is answering with “targeted pricing and affordability actions.” Its OA pain antibodies (Librela, Solensia) declined in Q4 2025 after leading growth in 2024, and Merck’s Bravecto line grew just 1% in 2025.
What it means for you: this is a good year to renegotiate. Parasiticides, dermatology and OA pain are the categories where suppliers are most motivated to offer rebates and bundles. Ask your reps directly.
Insured clients: 70 cents of every premium dollar goes to vets
Pet insurance is one of the healthiest corners of the industry, and most of that money ends up in veterinary practices. At Trupanion, vet invoices paid came to 70.2% of subscription revenue in Q2 2026, or $194M in a single quarter.
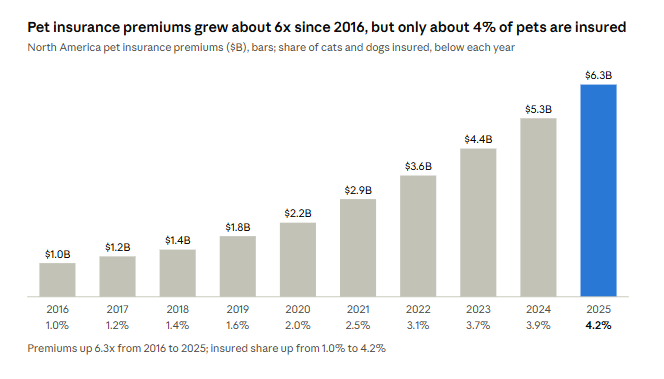
The catch is that recent growth is mostly price, not new pets. In 2025 premiums grew about 19% while the insured share rose only 0.3 points. Trupanion’s revenue per pet has risen about 10% a year, its total enrolled pets have slipped about 2% a year, and the UK sits at roughly 25% penetration by comparison. Insured owners are staying, though: Trupanion’s monthly retention improved to 98.37% in Q2 2026.
Financing is growing alongside insurance. Synchrony has named pets as a growth driver for CareCredit in every quarter since Q2 2025, and pet insurers Figo and Embrace now pay claim reimbursements straight into CareCredit accounts.
What it means for you: insured and financed clients are less likely to decline a recommended test or treatment. With only about 4% of pets insured, actively recommending insurance and offering financing is one of the few levers that lifts both acceptance and average ticket.
What it means for your practice’s value
If you’re thinking about selling in the next few years, the story buyers want to hear has changed. In a market where visits are shrinking for everyone, raw visit counts say less about a practice’s future than how much each visit is worth and where that revenue comes from.
The metrics that now tell the strongest story:
- Revenue per visit, and how it has trended over three years
- Diagnostics as a share of revenue, the line upstream companies see growing fastest
- Senior-patient mix, a proxy for the ageing pandemic cohort
- Wellness plan enrollment, which protects the visits retail is targeting
- Pharmacy and preventives, which a careful buyer will scrutinize for leakage to Chewy and other retailers
Financing for private buyers looks steady. At Live Oak Bancshares, a major lender to vet practice buyers, vet loans on its “special mention” watch list rose $18.4M in 2024, then fell $14.4M in 2025 while the bank’s overall watch list grew. That suggests credit stress among leveraged practice buyers peaked in 2024. Meanwhile, Patterson Companies, a top US vet distributor, was taken private for about $2.8B in April 2025, a sign that investors still want exposure to the clinical economy.
The bottom line: the practices that will command the best terms are the ones that can show they’ve adapted, growing revenue per visit, holding their wellness base and capturing the senior-pet wave, rather than relying on visit volume and annual price increases.
Wondering where your own practice stands? Get a free, discreet estimate with our Free & Easy Valuation, or read our article on normalized EBITDA in veterinary practice valuation.
Sources
- IDEXX: 10-Ks FY2024 and FY2025; prepared remarks Q2 2025 to Q2 2026; Investor Days August 2025 and August 2026
- Zoetis: earnings releases Q4 2024, Q4 2025, Q2 2026; Q2 2026 call transcript
- Elanco: earnings releases Q4 2025, Q2 2026
- Merck: earnings release Q4 2025
- Trupanion: earnings releases and call transcripts 2023–2026; shareholder letters FY2023–FY2025; 2025 Investor Day; Q2 2026 investor presentation (NAPHIA data)
- Chewy and Petco: 10-Ks FY2024 and FY2025
- Tractor Supply: VIP Petcare acquisition press release, May 28, 2026
- Synchrony: earnings releases Q1 2025 to Q2 2026
- Live Oak Bancshares: 10-Ks FY2024 and FY2025
- Patterson Companies: take-private 8-K, April 2025